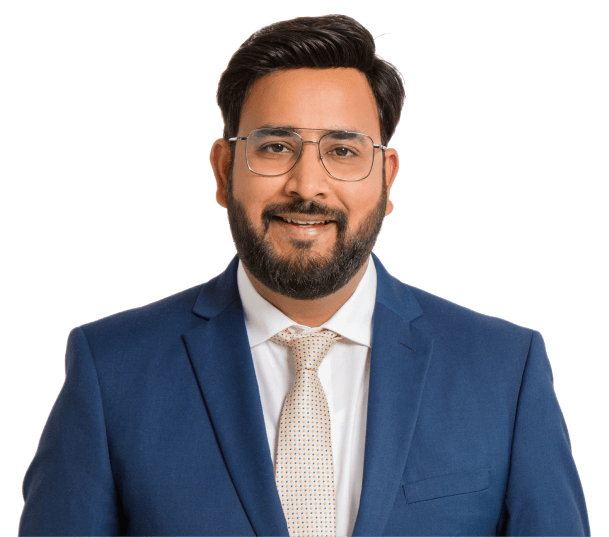
Your bank shows you one product. Amit shows you the market.
A bank advisor can only sell that bank's mortgages. Amit sends your file to the lenders most likely to say yes at the best terms, then lays the options side by side.
Amit is taking calls today
(437) 776-5148Licensed mortgage agent serving Waterloo Region and the GTA
One call and he compares 40+ lenders for you: big banks, credit unions and monolines. Buying, renewing or refinancing, you get real options within a day, explained in plain English. No cost to you on standard mortgages.
A bank advisor can only sell that bank's mortgages. Amit sends your file to the lenders most likely to say yes at the best terms, then lays the options side by side.
Penalties, prepayment limits and portability can cost you more than a slightly higher rate. Amit flags the fine print before you sign, not after.
Evenings and weekends included. When your offer is conditional and the clock is ticking, you get an answer the same day.
Most lenders let you lock a rate up to 120 days before your renewal date. Start shopping inside that window and you keep the option to take a lower rate if one appears. Pick your renewal month.
Pre-approval, down payment strategy, first-time buyer programs and 30-year amortizations.
Start a pre-approvalCompare your lender's renewal letter against the market and switch if the numbers say so.
Check my windowConsolidate debt, fund a renovation, or lower your payment. Penalty math done first.
See if it's worth itLenders that understand business income, write-offs and contract work.
Talk through my fileNewcomer programs that work with limited Canadian credit history.
Ask about newcomer optionsRental properties, HELOCs, and alternative lending when the bank says no.
Explore my options| Question | Your bank | Amit |
|---|---|---|
| Lenders compared | One | 40+ banks, credit unions and monolines |
| Who he works for | The bank | You. He is paid whichever lender wins. |
| Cost to you | Free | Free on standard residential mortgages |
| Self-employed or bruised credit | Often a no | Lenders built for these files |
| At renewal | A letter in the mail | A call 4 months ahead with options |
| Evenings and weekends | Rarely | Yes |
What you're buying or renewing, your income, your timeline. No credit check yet.
Two or three real lender options with rate, penalties and prepayment terms side by side.
You choose. Amit submits, handles the lender's questions and locks your rate.
He coordinates with your lawyer to close on time, then calls you four months before your next renewal.
Canadian semi-annual compounding, with mortgage default insurance added automatically when your down payment is under 20%. A quick estimate, not a quote.
For a real number based on your credit and income, ask Amit.
I've spent more than ten years helping Ontario families get into homes and out of bad mortgages, from first condos in Kitchener to move-up houses in Brampton. Over $110 million funded, across more than 200 files.
I'll tell you the truth about your options, even when the honest answer is "wait six months." I answer my phone, evenings and weekends included, because that's when most people have time to think about their mortgage.
I work with Dominion Lending Centres, which gives my clients access to one of the largest lender networks in Canada.
Some of the lenders Amit works with

Meet in person, by phone, or on video. Every document can be signed online, so where you live never slows you down.
Something else on your mind? Text Amit. He usually replies the same day.
For standard residential mortgages, no. The lender pays Amit when your mortgage funds. If your file needs a private or alternative lender, there may be a fee, and you'll see the exact amount in writing before you commit.
No. The first conversation involves no credit check. When you're ready for a pre-approval, Amit pulls your credit once and uses it to shop multiple lenders.
About four months before your renewal date. Most lenders will hold a rate for up to 120 days, so you can lock in early and still take a lower rate if one appears.
Often, yes. Since November 2024, if you move your mortgage to a new lender at renewal without increasing the amount or amortization, you no longer need to pass the stress test again. Amit will confirm what applies to you.
Often, yes. Several lenders accept tax returns or business bank statements and look beyond net income after write-offs. Going to the right lender first matters more than anything.
Usually one to two business days once Amit has your documents. You'll get a short checklist after your first call.